



In Judgment No. 27479 of July 21, 2026, the Third Criminal Section of the Court of Cassation ruled on the delicate distinction between a private collector’s mere enjoyment of artistic heritage and the conduct of a commercial activity, even if not on a regular basis, which may constitute the offense of making a false declaration under Article 4 of Legislative Decree No. 74/2000.
The case stems from charges of making a false tax declaration brought against a professional (a licensed physician) for failing to report, for income tax purposes, the (substantial) capital gain resulting from the sale of works of art and antique valuables, including a painting by Pablo Picasso, thereby constituting tax evasion exceeding the thresholds for criminal liability.
In confirming the defendant’s criminal liability, the Supreme Court referred to the well-established three-part distinction, developed by the Fifth Civil Section, between “art dealers” (whose sales generate business income pursuant to Article 55 of the Consolidated Income Tax Law [T.U.I.R.] and are subject to VAT); “occasional speculator” (whose sales are relevant solely for income tax purposes); and “collector” (whose sales have no income-related significance for either VAT or income tax purposes).
In defining the criteria for the legal classification of the taxable person, the Court of Cassation ruled that: “For the purposes of determining, pursuant to Article 67(1)(i) of the TUIR, miscellaneous income derived from commercial activities not carried out on a regular basis, in the context of the sale of works of art by private individuals, the identification of the taxpayer as an ‘occasional speculator’ is based on specific indicators such as the purpose of the purchase, the duration of ownership, activities aimed at facilitating the sale, an examination of the reasons leading to the sale, and the number and value of sales recorded over a three-year period or, in any case, with reference to a period exceeding a single calendar year.”
According to the Supreme Court, therefore, determining the speculative nature of the transaction is not limited to a piecemeal analysis of the individual sale, but requires a comprehensive, multi-year assessment of the taxpayer’s conduct. To this assessment, the Supreme Court adds (not without raising doubts from a systemic perspective) the economic magnitude of the capital gain realized. This is a conceptually tricky step: elevating the amount of profit to a factor indicative of speculative intent risks confusing the ex post financial result with the ex ante subjective element. The size of the economic margin (often dependent on unpredictable market revaluation dynamics or the rarity of the artwork) is thus transformed into a presumptive indicator of commercial intent, ultimately penalizing the mere success of a cultural investment rather than the actual conduct of a commercial activity.
With regard to the evidentiary framework suitable for determining the relevance of the sale for income tax purposes, the Supreme Court has clarified that: “The substantial capital gain derived from the sale of the painting must be classified as an occasional speculation (subject to taxation as miscellaneous income), and not as an isolated sale by a collector (not subject to taxation), when the prior occurrence of sales of works of art and antique valuables places the specific transaction within the scope of a commercial activity that, although not habitual, is characterized by the skillful display of the goods in a private residence to which wealthy clients are granted access, with whom a relationship of loyalty and personal trust is established.”
In other words, the number and frequency of sales, the use of promotional methods—even informal ones (such as displaying works in domestic spaces used as showrooms)—and the use of one’s professional network may constitute indicators of commercial activity, even if not regular.
In the author’s view, the automatic extension in criminal proceedings of the circumstantial criteria developed by civil tax case law raises significant issues of compatibility with the principle of specificity and certainty of criminal law.
As is well known, in administrative tax proceedings, proof of speculative intent may be based (though not without reservations) on mere indicative facts that suggest the significance of the transfer for tax purposes. However, in criminal proceedings, proving the objective and subjective elements of the offense requires a standard of proof sufficient to overcome all reasonable doubt; it cannot be reduced to the mere evaluation of ambiguous elements such as the“artful display” of works of art or“relationships of trust.” Mechanically transposing the fluid categories with extremely blurred boundaries—developed in the administrative sphere—into the framework of Legislative Decree No. 74/2000 creates a systemic short circuit that is unacceptable in law and completely detached from factual reality.
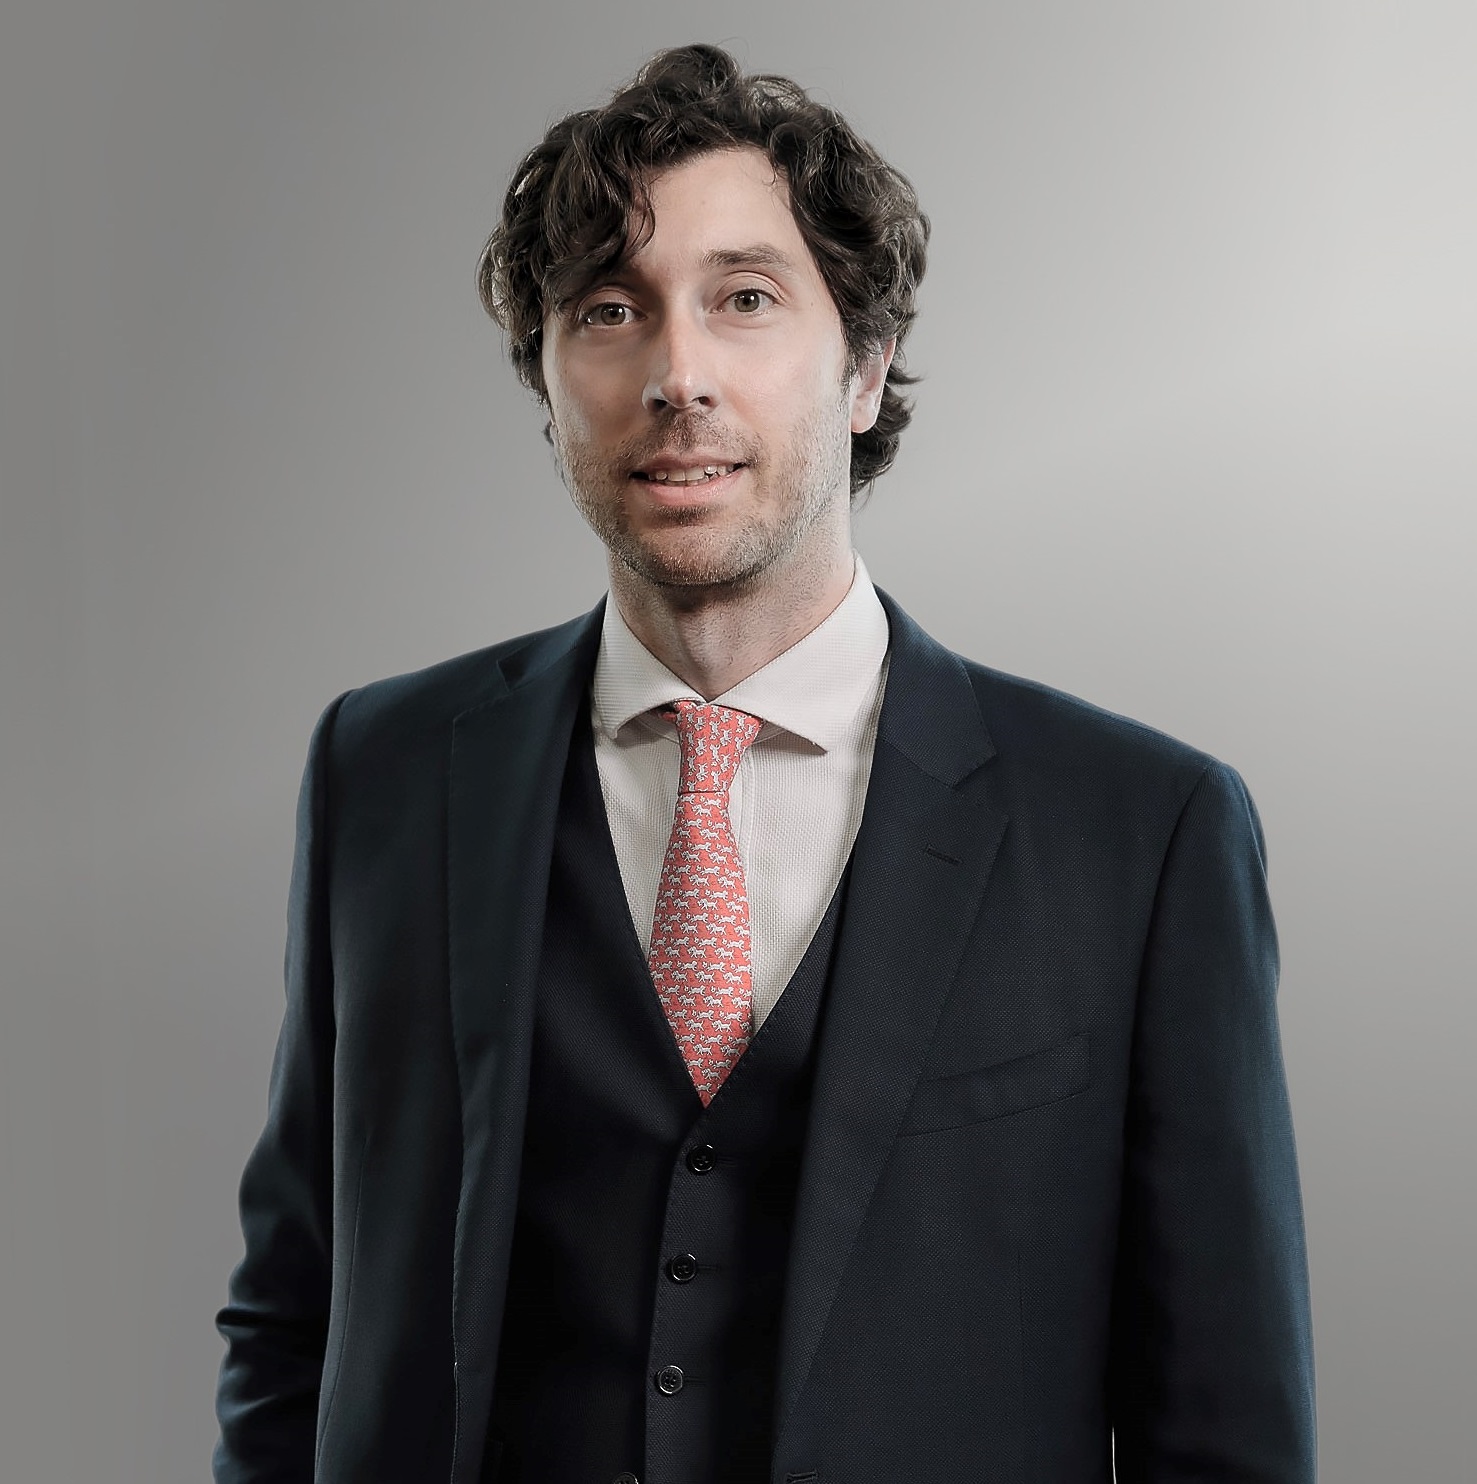
The author of this article: Marco Menozzi
Marco Menozzi, avvocato, è responsabile del Dipartimento di Diritto Tributario presso Effeffe & Partners Studio Legale, con sedi a Ferrara, Milano, Bologna e Roma. Ha maturato un’esperienza pluriennale nel contenzioso tributario relativo a tematiche di fiscalità nazionale e internazionale, con particolare riferimento alla fiscalità dell’energia e dei gruppi assicurativi e bancari. Assiste imprese e persone fisiche anche nella fase stragiudiziale e di interlocuzione preventiva con l’Agenzia delle Entrate, nei procedimenti di accertamento con adesione o mediante la redazione di istanze di interpello.Warning: the translation into English of the original Italian article was created using automatic tools. We undertake to review all articles, but we do not guarantee the total absence of inaccuracies in the translation due to the program. You can find the original by clicking on the ITA button. If you find any mistake,please contact us.






 IT
 FR
 DE
 ES
 CN


